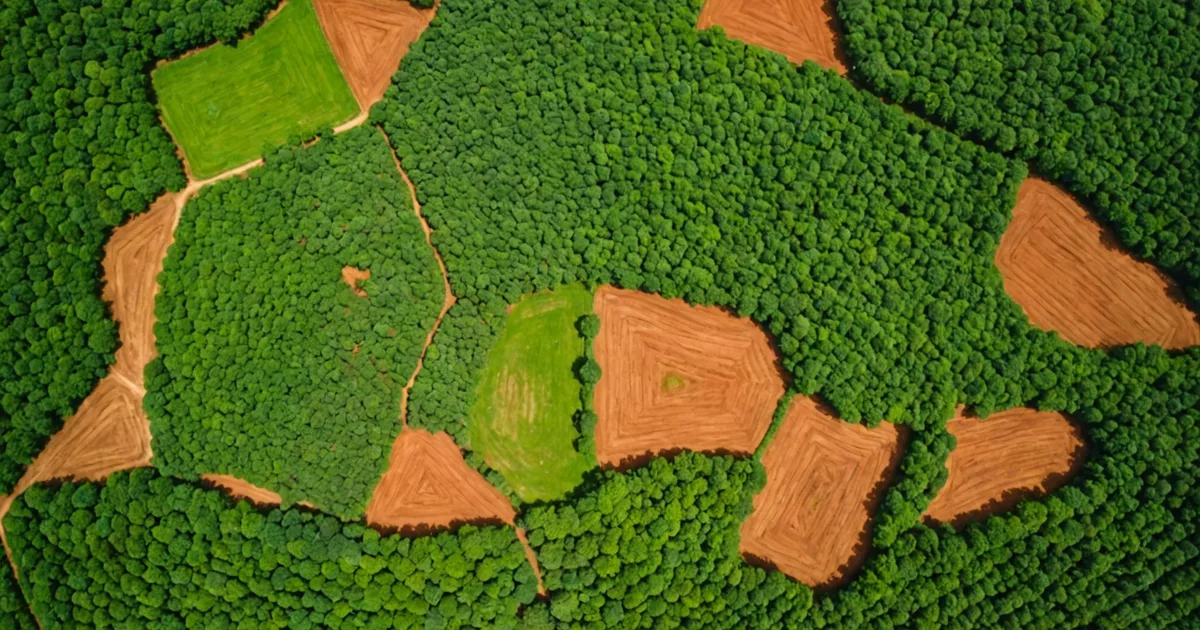
An 18-hectare farm in the Mantiqueira range may contain three very different plots: a 6-hectare block at 1,050 metres on well-drained, iron-rich latossolo, a 7-hectare area at 850 metres on shallower cambissolo with greater erosion exposure, and a 5-hectare lowland cerrado patch at 700 metres planted for expansion. A farm-level credit model combines all three into one score. A plot-level model evaluates each separately. The resulting credit decision is much more precise.
Why Farm-Level Scores Miss the Mark
For much of its history, agricultural underwriting has treated the farm as its unit of analysis. The borrower is a person, the property provides the collateral, and estimated income comes from the farm's total output. That framework is reasonable when a property is largely uniform, such as a flat, irrigated grain farm where soil and input practices remain consistent throughout.
Highland coffee production in Minas Gerais does not fit that pattern. A single property commonly includes altitude differences of 200 to 300 metres within the limits of one registered rural module. Soil also varies by slope position. Upper slopes generally contain deeper, well-drained latossolos with stronger water retention. Midslopes may contain cambissolos and nitossolos with differing organic matter, while valley floors can include gleissolos or organossolos exposed to waterlogging. These soils react differently to the same weather conditions and create different yield patterns under comparable management.
Reducing those differences to one farm-level score creates two recurring errors. The first is approving credit based on production expectations supported by the farm's strongest plots, even though weaker plots reduce the actual average yield. The second is rejecting a grower whose strong high-altitude block could readily support the loan because lower-quality lowland plots raise the property's apparent risk when averaged together.
What a Plot-Level Score Requires
Shifting from farm-level to plot-level scoring depends on two inputs that the broader approach lacks: GPS boundaries for each plot, and a way to connect agro-environmental data to every polygon instead of the property centroid.
Capturing GPS boundaries is the first technical step. Through our platform, a grower can draw plot limits in the mobile application or upload a KML file from the CAR rural environmental registration. This registration is required for all rural properties in Brazil and records property perimeters at parcel level. We ask growers to separate active coffee plots from other land uses within the property. Internal divisions are not precisely mapped by every grower, which limits the method in practice and is partly addressed through aerial imagery review.
After the plot polygons are defined, data extraction uses geospatial queries across several public and national datasets. Sentinel-2 NDVI time series are calculated for each polygon. EMBRAPA's SolosWeb soil classification database supplies the dominant soil type and texture class at each polygon's centroid. SRTM elevation data supplies mean altitude and slope characteristics. INMET weather data is interpolated to each polygon's location and altitude rather than one property centroid. The output is a profile for every identified plot, rather than one profile for the entire property.
The Plot-Level Scoring Model
The model evaluates each plot polygon and returns a risk score from 1 to 100 with a confidence band. Its main components are production potential, derived from NDVI and weighted by altitude zone, soil suitability, based on EMBRAPA classification indexed to Sul de Minas arabica production standards, weather exposure, measured through frost-corridor risk and rainfall variability, and yield consistency, using cooperative delivery history where available and assigning it to the delivering property rather than individual plots.
At plot resolution, yield-history attribution is the model's weak point. Cooperatives log deliveries by grower identifier, not by plot. Someone managing three plots delivers as one grower. Assigning past yield to separate plots therefore requires the grower's own per-plot harvest records or a production-potential model that allocates total yield according to estimated productivity. We use the latter by default and mark its use in the confidence band when plot-specific records are missing.
For the 18-hectare example above, the model could assign 74 to the high-altitude latossolo block, 58 to the mid-altitude cambissolo section, and 41 to the lowland cerrado patch. The first plot qualifies for credit at the standard rate for its plot-size tier. The second qualifies with conditions. The third would not qualify as an independent credit basis. Weighting the three scores by hectares gives a farm-level average of 58, a conditionally approved profile under our current thresholds. The plot-level picture is more informative: credit can be sized around the productive capacity of the strongest blocks, instead of asking the lowland expansion area to support part of the income estimate.
From Score to Loan Design
Plot-level scoring does more than refine risk measurement. It changes loan structure. If 11 of the 18 hectares show strong production potential and the other 7 are marginal, the loan can be based on expected cash flow from the 11 productive hectares, leaving the marginal block out of the repayment-basis calculation. The result is smaller than a farm-level model might indicate, but more reliably serviceable.
This cautious sizing is important. Smallholders in Sul de Minas have limited financial reserves. A loan based on an optimistic farm-level score that includes marginal land in projected income can create a debt-service obligation greater than the productive plots can cover in an ordinary year. The borrower may then default despite no agronomic failure, simply because origination overstated capacity.
Our loan tiers reflect this approach. The Micro tier (up to 5 hectares, R$5,000 to R$20,000) is set for the working capital needs of a smallholder qualifying one high-quality plot. The Grower tier (5 to 20 hectares, R$20,000 to R$60,000) serves borrowers with several plots and a consistent production record. Within each tier, the loan amount depends on the plot-level risk score and productive-hectare basis, not total farm area.
GPS Boundary Data: A Practical Limitation
The precision of the plot-level model depends directly on the quality of the GPS boundaries submitted with an application. An applicant who draws rough limits in the mobile application, or uploads a CAR registration showing only the property's outer perimeter without internal plot divisions, reduces the resolution available for scoring.
We do not claim that every Culttivo application delivers a perfectly mapped multi-plot assessment. When an applicant lacks accurate internal boundaries, the model works at property level with the data available. The score's confidence band shows this lower resolution. A property-level assessment with broad confidence bands may still support a credit decision, but loan sizing becomes more conservative because of the uncertainty.
We accept this tradeoff. Boundary data should improve as mobile GPS tools advance and more growers complete detailed CAR sub-parcel registrations. Asking applicants to create false precision merely to meet the model would create another error. The model uses what applicants can genuinely provide and states its uncertainty instead of concealing it.
Why This Method Matters Beyond Individual Loans
Plot-level scoring affects more than individual credit decisions. A portfolio assessed at plot level lets the lender identify the geographic and agronomic basis of the production claim supporting each credit position. Exposure can be aggregated by altitude zone, soil type, and weather corridor. If frost affects a particular valley corridor in winter 2026, a lender with plot data can identify the exposed loans and contact those borrowers before defaults appear.
This provides the foundation for agricultural lending at scale in Brazil's smallholder coffee market: not only stronger individual loans, but also a portfolio view that can be managed. Plot-level data is the foundation. Farm-level and borrower-level records cannot provide the same visibility because they lack the geographic detail needed to connect risk exposure with specific agronomic events.